There’s a lot riding on John Healey’s first Budget on 28th October. He has the job of putting some numbers on Andy Burnham’s pledge to deliver ‘good growth in every postcode and hope in every heart’ against a lousy fiscal and economic backdrop. He inherits ten-year gilt yields above 5%, national debt of nearly £3tn (and growing), and little room to manoeuvre. On top of that, there’s the Labour manifesto and the pledge not to raise income tax, National Insurance or VAT – the government’s three biggest tax levers. To calm the bond markets, the Chancellor must improve the country’s balance sheet. This means spending cuts, tax increases, or both. Spending cuts sit awkwardly with a government that’s promised growth, not austerity. So that leaves tax. Increasing the total tax take could come from growing the economy, but this is a longer-term ambition rather that the quick fix that’s needed. That’s why tax increases feel almost inevitable. With limited options available, it’s increasingly likely that Healy will look to capital gains tax (CGT) in some way. Moving parts: CGT and income tax over 60 years and 20 Chancellors “The failure to tax capital gains is widely regarded… as the greatest blot on our existing system of direct taxation… earnings pay tax in full while capital gains go free. This is unfair to the wage and salary earner.” – Chancellor James Callaghan, 6th April 1965 “We need a wealth tax that works. A pound made simply from owning assets should not be taxed less than a pound made from a hard day’s work.” – Wes Streeting, 21st May 2026 There have been 20 different UK Chancellors since 1965 when James Callaghan first introduced CGT at an initial rate of 30%. All have had their own view on how to tax gains on asset sales. Nigel Lawson (a Conservative) even fully aligned CGT with income tax rates in 1988. The question of what is ‘fair’ has never gone away. With Andy Burnham admitting that we need a “greater sense of fairness”, and several senior Labour figures (including Defence Secretary – and one time leadership rival – West Streeting) calling to align CGT rates with income tax rates once again, it would appear that at least an incremental rise to CGT rates is plausible. It’s hard to know what changes might come, so rather than guessing, it’s better to make sure clients’ plans hold up whichever way the Chancellor moves. For those that rely on realising gains to fund purchases, lifestyle or one-off liquidity events, rises in CGT rates are a real risk. Thankfully, Lombard lending offers potential solutions. Realising the problem: the alternative to selling down investment portfolios for liquidity Even if tax rates on income and capital gains get more closely aligned, income and gains themselves remain fundamentally different. Income is taxed the moment it’s earned; gains have to be realised to be taxed. A paper gain sitting in a portfolio owes nothing until it’s sold, meaning the goal isn’t avoiding gains but avoiding unnecessary realisation to fund liquidity. 1. The Elon Musk approach to liquidity Elon Musk didn’t only sell Tesla stock to buy Twitter (now X). He borrowed against it, pledging shares as collateral rather than realising a gain to fund the deal. That’s Lombard lending, a loan secured on an investment portfolio rather than money raised by selling out of it. The same logic can work for wealth management clients. Our Lombard facilities can be secured against a client’s investment portfolio: up to 50% of portfolio value, with loans from £65,000. Like an overdraft, the available facility is continually available for when liquidity is required, drawn and repaid flexibly, secured against their investment portfolio, with no need to sell assets. Take the example of a client selling down £250,000 from their portfolio for liquidity. At 24% CGT (current rate), a tax liability of £24,000 could be triggered the moment the trade settles (assuming the 40% of the £250,000 is gains and the client has already used their £3,000 tax-free allowance). Borrowing the same amount costs only the interest accrued for as long as the facility is needed and the portfolio stays intact and keeps working. You’re not choosing between tax and no tax. You’re choosing between the cost of borrowing and the cost of selling, and that trade gets better for borrowing the higher CGT goes. It doesn’t rule out selling later either. It just lets you choose the moment, a better tax year, a loss to offset, a calmer market, instead of a liquidity need forcing your client’s hand. 2. Don’t spend what you can’t rebuild With the tax burden in the UK at a 70-year high (and seemingly heading in only one direction), the importance of maximising and preserving tax-efficient investment wrappers is more important than ever. Take an ISA as an example: the ISA allowance is £20,000 a year and can’t be backdated. To rebuild £150,000 withdrawn from an ISA would take the better part of a decade. And you would lose out on the assets continuing to grow free tax. Offshore bonds work on the same principle. Growth inside the bond compounds free of UK tax each year, but only for as long as the money stays invested. Withdraw a segment, and that capital loses the wrapper for good, and your client loses the ability to choose when, and to whom, any eventual gain is taxed. Firenze’s Lombard facilities can be secured directly against ISAs and most offshore bonds. Your client isn’t choosing between preserving the wrapper and having liquidity, they get both. The ISA of bond keeps compounding untouched, and the value it represents is available as borrowing power whenever it’s needed, doing two jobs at once: protecting capital in the most tax-efficient corners of the portfolio, and keeping liquidity on tap beside it. 3. Where CGT goes to die: Unlike other taxes, CGT does not apply on death. When someone dies, their portfolio asset’s
Estate planning. Many clients may distance themselves from the thought of having to plan for when they’re gone. It can be a difficult conversation
There’s a lot riding on John Healey’s first Budget on 28th October. He has the job of putting some numbers on Andy Burnham’s pledge
Banking infrastructure is being rebuilt from the inside out. Across the industry, banks are re-platforming credit, custody, and client servicing onto fintech that sits
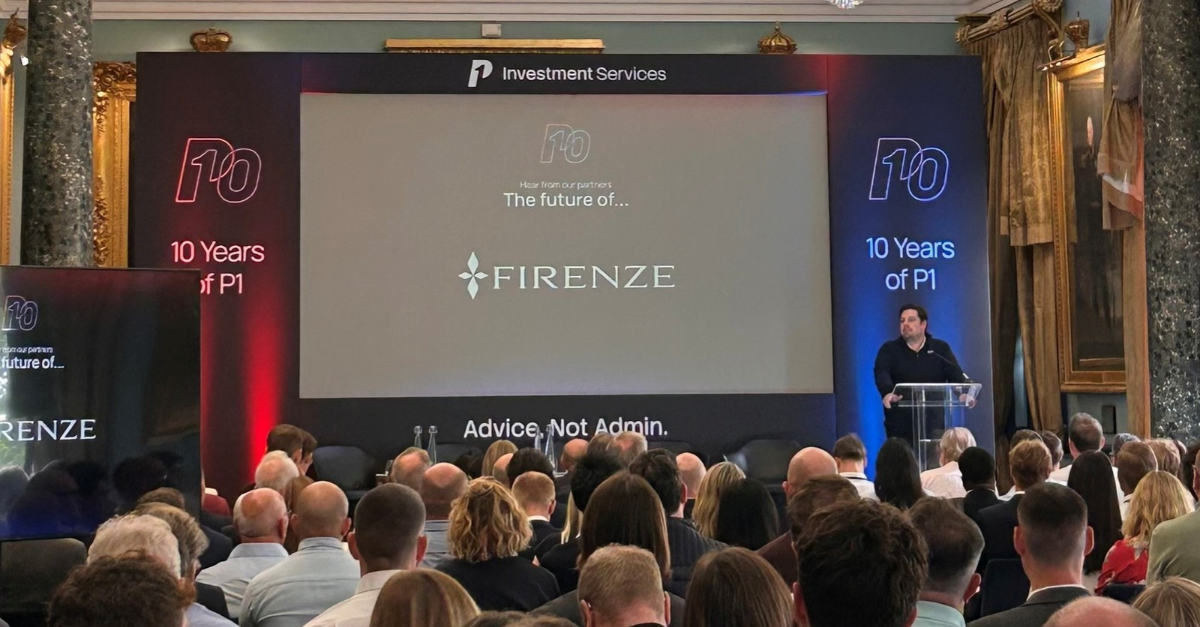
Our trusted partner, P1, celebrated a landmark milestone of ten years in business last week. To acknowledge, the firm hosted P10 – a gathering

While not a surprise bill to be landing on many parents’ doorstep each year, fees for schools and university tuition can still land at

Why entrepreneurs borrow against their investment portfolio instead of taking a business loan Firenze can lend to individuals, joint borrowers, and crucially for entrepreneurs,
