Estate planning. Many clients may distance themselves from the thought of having to plan for when they’re gone. It can be a difficult conversation to address, but getting this wrong can be even more difficult for those left behind.
A Lombard facility lets a parent gift money to the next generation today without selling their investment portfolio and manage their inheritance tax (IHT) bill. It’s an especially effective tool when property deposits come into consideration.
Having the peace of mind that their children or grandchildren have secured homes takes weight out of the estate planning conversation. That’s why this structure has proven popular with our existing clients and clients of private banks for generations.
Why is gifting so hard when wealth is tied up in investments?
Many families want to pass wealth down early, but their assets are invested rather than held in cash. Selling to fund a gift can trigger capital gains tax (CGT), take money out of the market at the wrong time, and disrupt a long-term investment strategy.
The pressure to act is rising. IHT thresholds remain frozen, and from April 2027 most unused pension funds are due to fall into the estate for IHT purposes. Careful planning is essential for families with significant estates.
Our client, Heather*, understood the gravity of effective estate planning. With a £2.5 million portfolio, she wanted to maximise the opportunities for her daughters without subjecting them to substantial inheritance tax or CGT implications.
Here’s how we helped.
Funding her daughter’s property portfolios with Lombard lending
Heather’s daughters wanted to expand their property portfolio beyond those in Heather’s name. She also didn’t want to subject them to higher rates of IHT they would face should they wait for her to pass.
However, selling investments to fund this expansion would have meant reducing the overall value of the portfolio she was due to pass onto her daughters, and reduce the value of funds available for her later life care.
Instead, a Lombard facility provided the estate planning solution they needed.
| Detail | |
|---|---|
| Portfolio value | £2,500,000 |
| Lombard facility | £1,000,000 |
| Loan-to-value | 40% |
| Gift to each daughter | £500,000 |
| Use of funds | Deposits and purchases for her daughters’ London property portfolio |
| Portfolio sold | None |
| Potential IHT saving | £400,000 |
How does the £1 million Lombard facility work?
The mother borrows against her portfolio and gifts the cash; the portfolio itself never changes hands. The structure runs in five steps:
- Pledge – The portfolio stays with her existing wealth manager and custodian and is pledged to Firenze as security.
- Draw down – We approve £1 million, 40% of the portfolio’s value and well within typical lending limits for a diversified portfolio.
- Gift – She gifts £500,000 to each daughter outright. Each gift is a potentially exempt transfer (PET) for IHT purposes after seven years.
- Invest in property – The daughters use the funds for deposits and purchases within their London portfolio.
- Service and repay – Interest is paid from portfolio income or other resources. The loan can be repaid later from planned disposals, other assets, or ultimately the estate upon death.
The wealth manager keeps managing the portfolio throughout. Assets are retained, the strategy continues as planned, and no gains are realised.
What are the estate planning benefits?
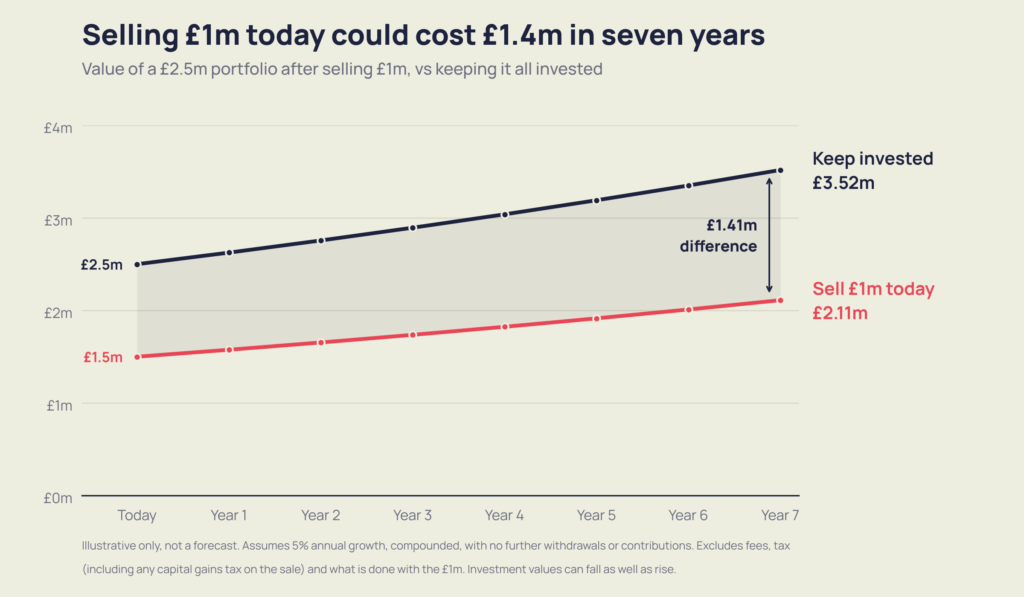
If the mother survives seven years, the £1 million gift falls outside of her estate entirely, a potential IHT saving of up to £400,000 at the 40% rate. The facility also delivers benefits that selling assets could not:
- The seven-year clock starts now – Gifting today rather than waiting until assets can be sold brings forward the date the gifts become IHT-free.
- No CGT is crystallised – Selling £1 million of a portfolio with large, embedded gains could create a significant CGT bill. Borrowing avoids crystallisation altogether.
- The portfolio stays invested – The full £2.5 million remains in the market, with its income and long-term strategy intact.
- The next generation benefits sooner – The daughters grow their property portfolio now, and any future growth on those properties accrues outside their mother’s estate from day one. They will also inherit more.
What are the risks and considerations when using a Lombard facility?
The main risk is a fall in portfolio value pushing the LTV towards the lender’s limit. At 40%, this facility leaves meaningful headroom.
| Portfolio fall | Portfolio value | LTV on £1m loan |
|---|---|---|
| None | £2,500,000 | 40.0% |
| 10% | £2,250,000 | 44.4% |
| 20% | £2,000,000 | 50.0% |
| 30% | £1,750,000 | 57.1% |
Other points the adviser and client should weigh:
- Margin calls – If the LTV breaches the agreed limit, the client may need to add assets, repay part of the loan, or sell investments.
- Interest costs – Interest is charged on the loan and should be weighed against expected portfolio returns and the potential IHT saving.
- Professional advice – The IHT, CGT, and debt-deduction rules are complex. Advice from a qualified tax specialist is essential before proceeding.
How do advisers put a Lombard facility in place for their clients?
For the adviser, Lombard lending turns an estate planning conversation into a practical solution. Clients can gift now, keep their portfolio working, and give the next generation a head start, all while the adviser retains the assets and the relationship.
To ensure the client can reap the potential benefits of Lombard lending, it’s vital advisers take the time to make sure they understand the product. Clients should also be aware of risks and understand the rates and terms of the facility.
Successful implementation could open the door to further opportunities for clients to borrow against their investments. Financing new cars, unlocking liquidity for life events, or even for investment in business opportunities – portfolio-backed lending doesn’t need to be a one-and-done transaction.
Frequently asked questions
Can you use a Lombard loan to fund a gift to your children?
Yes. A Lombard loan provides cash secured against an investment portfolio, and the borrower can use that cash to make gifts. The gift is usually a potentially exempt transfer, which falls outside the estate for IHT if the giver survives seven years.
Why borrow against a portfolio instead of selling it to make a gift?
Borrowing avoids crystallising CGT and keeps the portfolio fully invested. Selling can trigger a CGT bill and remove capital from the market, while a Lombard facility leaves the investment strategy unchanged.
How much can you borrow against a portfolio?
It depends on the assets held, but we can lend up to 50% of the value of the portfolio.
Can the gifted money be used to buy property?
Yes, once gifted, the money belongs to the recipient who can use it for property deposits or purchases. The giver must not benefit from the property, or the gift may be treated as a gift with reservation and stay in their estate.
What happens if the giver dies within seven years?
The gift becomes chargeable to IHT. If the gift exceeds the nil-rate band and death occurs between three and seven years after it, taper relief reduces the tax due on a sliding scale.
*Names and information have been altered to protect identity.